Institutions & Power · Housing · Legacy & Insights · July 2026
Congress Found Its Housing Villain. The Numbers Refuse to Stay Simple.
A bipartisan law just capped how many single-family homes one company can own. In the neighborhoods where that ownership is actually concentrated, the cap arrives generations after the damage was done.
Lawmakers from both parties agreed to restrict investors who own a fraction of one percent of America’s homes. In Atlanta, where that ownership concentrates in the rental market specifically, the real fight was over decades before this bill existed.
In 2021, Henry County Commission Chair Carlotta Harrell put her house up for sale and got cash offers from investors right away. She turned down every one of them and sold to a family instead — a broker named Oriana Wyche, buying a bigger place for her own household of five. Multiply Harrell’s refusal by the number of Atlanta homeowners who didn’t refuse, and you start to see the shape of a housing fight Congress just voted, almost unanimously, to settle with a law aimed at less than one percent of the market.
What This Article Is Actually About
This isn’t a story about whether one housing bill is good policy, and it isn’t a story that treats the bill’s defenders as arguing in bad faith — some of their strongest points are real. It’s about what a national consensus can agree to fix, and what it quietly leaves alone: a law aimed at a small national number, landing hardest in specific neighborhoods with a specific, decades-long history the bill never mentions.
Signal One
The Consensus
Both parties applauded a cap on institutional home-buying — a rare bipartisan agreement, built around a target controlling under 3 percent of homes nationally.
Signal Two
The Real Defense
Housing economists and industry leaders make a genuine case that the bill’s target may already be shrinking on its own — and that matters.
Signal Three
The Harder Number
In metro Atlanta, institutional ownership of single-family rentals reaches roughly 30 percent — concentrated in neighborhoods shaped by redlining and the 2008 foreclosure crisis.
I. The Villain Everyone Agreed On
The 21st Century ROAD to Housing Act bars any single entity from owning more than 350 single-family homes, new construction exempted. It passed with real bipartisan support, and lawmakers on both sides praised it as the moment Washington finally stood up to Wall Street landlords — a genuinely rare thing in this Congress. It is also, by the numbers most commonly cited, aimed at a target controlling somewhere between 0.66 and 3 percent of all single-family homes in the country, according to the Government Accountability Office and industry research, depending on which ownership threshold defines “institutional investor.” Freddie Mac’s own research team, writing about what actually drove the past several years of home-price growth, put it plainly: “What may surprise you is that investors don’t make our list of top drivers.” Mortgage rates, decades of underbuilding, and migration patterns did that work instead. This bill does not touch any of them. It is one provision inside a much larger, 47-provision housing package covering zoning, construction speed, and financing — but the provision that got the applause, the one both parties could stand next to without flinching, was the one aimed at the smallest number in the entire bill.
II. The Case for the Bill’s Defenders
That would be the end of the story — a safe villain, a real crisis left standing — except the defenders of this bill have a real argument, made by real people, and it deserves to be heard before it’s answered. Dave Howard, head of the National Rental Home Council, points out that homeownership rates in metro Atlanta are actually higher today than they were in 2016. Laurie Goodman, who founded the Housing Finance Policy Center at the Urban Institute, has cautioned that it’s genuinely difficult to separate what large investors did to Atlanta homeownership from what the 2008 foreclosure crisis itself did — the two happened at the same time, in the same neighborhoods, and untangling cause from correlation is real, serious work, not a dodge. Even the fiercest critics of this bill’s target, at outlets like Better and UBS, note that Blackstone’s own single-family purchases are down more than 90 percent since 2022 — institutional buyers may already be retreating on their own, cap or no cap. That is the strongest version of the case that this bill, even if it’s aimed at a small number, might not need to do much, because the number was already shrinking.
What Isn’t in Dispute
Blackstone’s single-family home purchases are down more than 90 percent since 2022, per UBS research citing the company directly — institutional buying nationally does appear to be retreating on its own. At the same time, in metro Atlanta specifically: institutional investors control roughly 30 percent of single-family rental stock — a different measurement than the national all-homes figure above, but a real concentration by any measure — with three corporations alone holding nearly 20,000 homes in the metro, seven firms holding more than 51,000 using various corporate names, and ownership reaching 80 percent in some neighborhoods. Both of these things are independently documented. Neither one cancels the other out.
III. The Harder Number
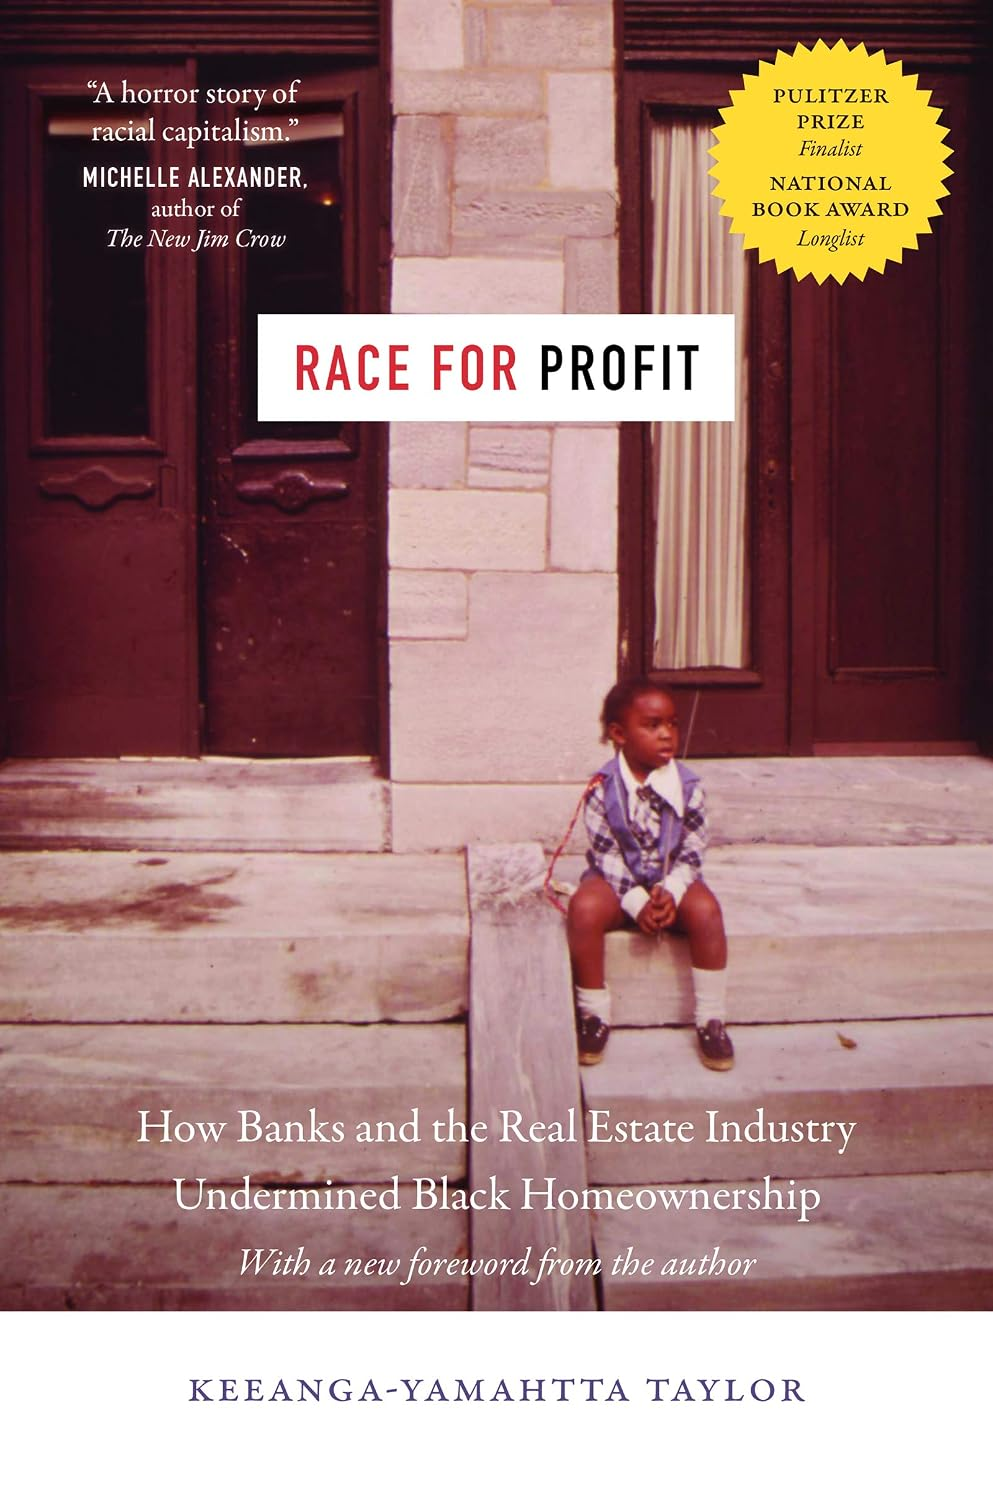
Here is where that case runs into a harder number — one measured a different way, and worth being precise about. The national figure above is institutional ownership as a share of all single-family homes. In metro Atlanta specifically, institutional investors now control roughly 30 percent of the single-family rental stock — a narrower category, and not a figure directly comparable to the national one — according to a 2026 report from the American Economic Liberties Project. Even accounting for that difference in what’s being measured, the concentration is real: three corporations alone control nearly 20,000 homes in the metro area; seven firms, using a web of corporate aliases, own more than 51,000. In some neighborhoods and counties, investor ownership reaches 80 percent of single-family rentals. And an Atlanta Journal-Constitution investigation found that Wall Street landlords are more than twice as likely to buy homes in Black neighborhoods as in comparable white ones. Homeownership rising citywide, as Howard notes, is compatible with a specific set of neighborhoods losing ground the whole time — a city-level average can rise while a dozen ZIP codes are quietly being converted from owned homes into rental portfolios.
IV. Redlining Didn’t End. It Changed Owners.
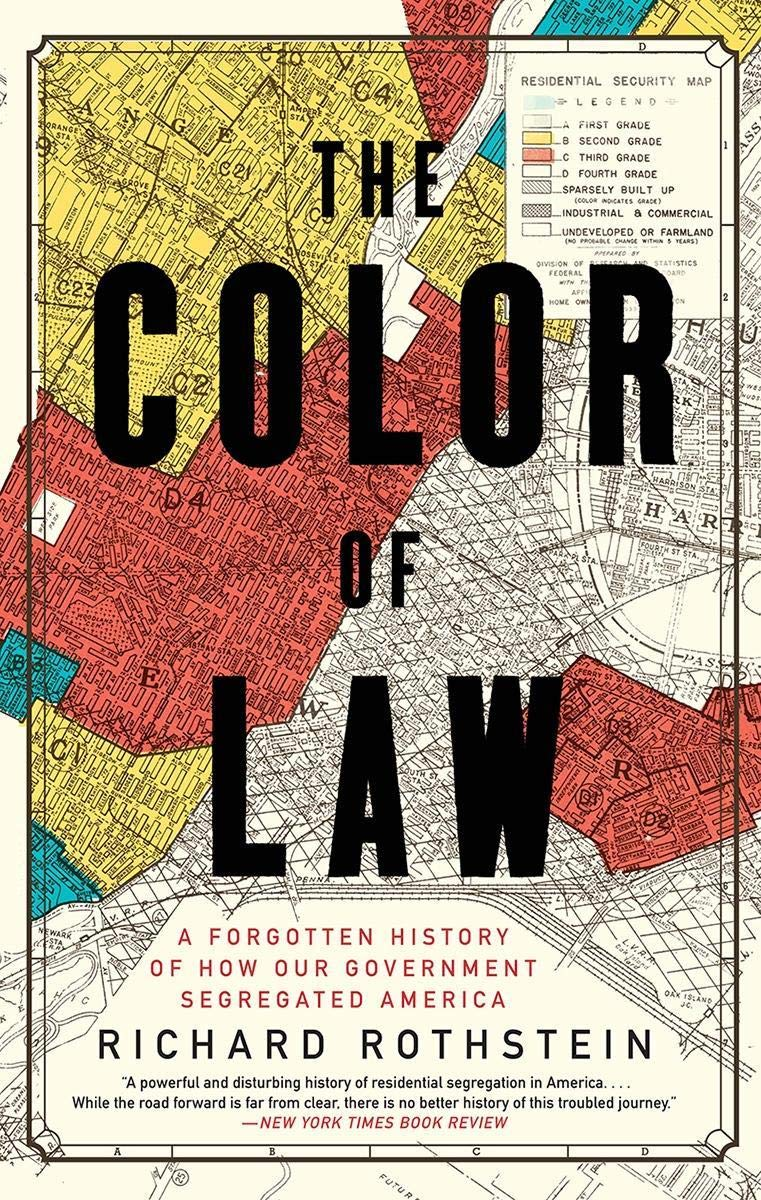
That targeting did not start with a hedge fund. It started with redlining — decades of federal and private maps that decided, block by block, which neighborhoods were worth a mortgage and which were not, systematically excluding Black families from the ordinary path to homeownership that white families were offered without a second thought. It continued through the 2008 foreclosure crisis, which hit Atlanta harder than almost any city in the country — home prices fell 17.7 percent in 2012 alone, the steepest drop nationally — and emptied exactly those same excluded neighborhoods of homeowners at scale, at the precise moment institutional capital, freshly organized after the crash, was hunting for cheap, plentiful houses to buy in bulk. Weak Georgia tenant protections and fast eviction timelines made the state an easy place to operate once the buying started. None of that means Goodman is wrong that cause and correlation are hard to separate here — they are. It means the harder question isn’t whether investors alone caused the decline in Black homeownership. It’s whether a market already this uneven was ever a fair one for a family like Carlotta Harrell’s neighbors to compete in, cash offer against cash offer, long before this bill existed.
V. What the Law Actually Fixes, and What It Doesn’t
None of this makes the 350-home cap meaningless. Slowing future acquisition in the handful of metro areas holding the largest share of institutional inventory is not nothing, and it may help at the margins in neighborhoods still being actively targeted today. But a policy built to answer “did we do something about corporate landlords” is a different policy than one built to answer “did we address which neighborhoods lost a generation of homeownership, and why those neighborhoods in particular.” Congress passed the first question this year. Nothing in the bill’s other 46 provisions requires it to seriously attempt the second. Housing affordability in America has real, well-documented causes — thirty years of underbuilding, financing costs, zoning that keeps supply artificially low exactly where people most want to live. All of those are harder to fix than a 350-home cap, because all of them require confronting builders, local governments, and existing homeowners who benefit from scarcity — constituencies with far more political weight in a district than an investment fund’s holding company will ever have.
Carlotta Harrell had the option to take the cash and the choice to say no. Most homeowners in the neighborhoods this bill is supposed to protect never got that option to begin with — the houses were already gone before they were old enough to bid on them. A 350-home cap is a real, defensible start. It becomes a serious answer only if the next housing bill asks the harder question this one skipped: not just how many homes one company can buy going forward, but which families never got the chance to buy in the first place, and what it would actually take to open that chance back up.
KMOB1003 Framework
The Safe Villain Test
Scale & Concentration
How much of the problem does this actor control nationally — and where does that comfortable average conceal a very different local reality?
Cost
How politically safe was it to choose this particular target, and who didn’t have to be confronted to pass the bill?
Consequence
Will restricting this target actually change prices, availability, or ownership where the damage is worst — or mainly change the headline?
Silence
Which harder causes, and which specific communities, absorbed the real damage while the safer conversation happened in public?
A national average can minimize a local wound. A local wound can exaggerate a national cause. Serious policy must survive both truths.
Signal Breakdown
Signal: A bipartisan housing law targets institutional investors who own well under one percent of the nation’s single-family homes — a number that is also, independently, already shrinking.
Impact: In the metro areas where that ownership actually concentrates — especially historically Black neighborhoods shaped by redlining and the 2008 foreclosure crisis — a 350-home cap changes little about who already lost ground, and why.
Watch: Whether the next housing bill is built to address where capital actually concentrated and whom it targeted, or continues to target whichever number is safest for both parties to agree on in public.
The Question the Next Housing Bill Has to Answer
A 350-home cap tells a company how many houses it can buy tomorrow. It says nothing about which houses, in which neighborhoods, were already gone by the time this bill was written — or who would have owned them instead.
Creator & Institutional Infrastructure
Genspark
Trace a Number Back to Its Source
This piece depended on knowing which “institutional investor” statistic came from which threshold, and which claim was Freddie Mac’s own research versus someone else’s summary of it. Use Genspark to build that kind of source trail before a repeated figure becomes an assumed one.
ElevenLabs
Get a Local Story to a National Audience
A story like this one lives or dies on whether it reaches people outside the ZIP codes it’s actually about. Use ElevenLabs for clearly disclosed narration and multilingual access that carries local reporting past its original audience.
OpenArt
Show a Map, Not Just a Percentage
A concentration this uneven is often clearer as a map than as a paragraph of numbers. Use OpenArt for distinctive, clearly disclosed visuals that make a geographic argument legible at a glance.
NordVPN Complete
Protect Reporting on Property Records
Pulling ownership records, corporate aliases, and public filings on institutional buyers is exactly the kind of research worth doing privately. Use NordVPN Complete to keep that workspace secure while a story is still being built.
Disclosure: KMOB1003 may earn a commission from qualifying purchases through select partner links. Editorial coverage is produced independently.
The Operator’s Bookshelf
KMOB1003 READS
As an Amazon Associate, KMOB1003 may earn from qualifying purchases.
Disclosure: KMOB1003 may earn a commission from qualifying purchases through select partner links. Editorial coverage is produced independently.
KMOB1003 After the Article
Continue the Signal
One article is a signal. Here’s where the pattern keeps building.
One Bill Is a Signal
Continue the Institutions Series
Continue exploring how institutions, industries, leadership, and public life are adapting to structural change.
Enter Legacy & Insights →
Every Cost Eventually Lands Somewhere
The Cloud Has a Utility Bill. Communities Are Refusing to Pay It.
A different infrastructure fight — over data centers, not housing — raises the same question: who absorbs a cost that a consensus never priced in.
Read the Analysis →
The Infrastructure Layer
Creator & Business Infrastructure
Explore research, publishing, workflow, protection, communication, and business systems selected for creators, founders, and operators.
View the Infrastructure →
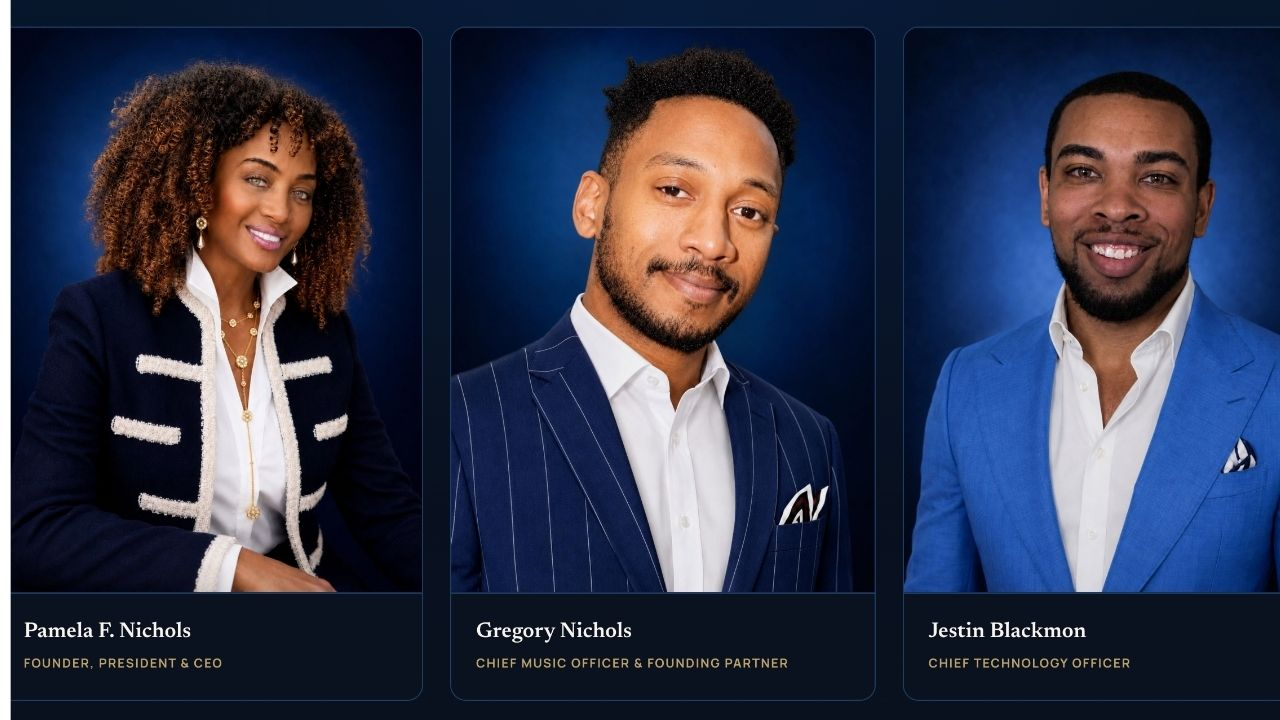
Meet the Institution Behind the Signal
KMOB1003 Leadership
Meet the leadership building KMOB1003 as independent cultural infrastructure for a changing media, business, and technology economy.
Meet the Leadership →
Global Reach. Powerful Stories. Lasting Impact.
